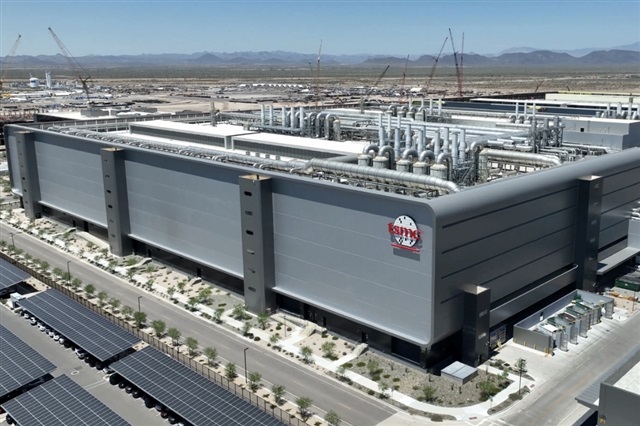
Samsung Electronics plans to produce high-bandwidth memory (HBM) base dies for AMD at its second foundry plant in Taylor, Texas, with the US chipmaker accounting for most of the facility's planned output, South Korea's Maeil Business Newspaper reported on November 3, citing industry sources. The report said the plant would also supply Nvidia, although Samsung has not confirmed either customer's orders.
High Bandwidth Flash (HBF) could give AI accelerators more memory at roughly one-tenth the manufacturing cost per gigabyte of HBM4. But producing it could consume far more wafer capacity than conventional NAND, potentially tightening supply for SSD makers.
Panasonic Industrial Devices Materials Taiwan's Hukou plant experienced an explosion and fire early on November 4, injuring five employees and leaving two others unaccounted for. The fire continued to spread through the five-story, steel-framed, metal-clad facility, while the cause and extent of the damage remained under investigation.
SK Hynix's decision to halt evaluation of a Solidigm pre-IPO and IPO has renewed questions over how it will finance a planned NAND flash plant in the US. Selling remaining assets linked to its investment in Kioxia has emerged as a potential funding option, but Kioxia's share-price decline and the investment's strategic and shareholder value have complicated the timing and necessity of any sale.
AI demand continues to heat up while major global memory makers shift capacity toward higher-value products, keeping niche memory supplies tight in the near term. China-based IC design firm GigaDevice Semiconductor Inc. said niche DRAM prices have risen sharply, curbing some consumer-electronics demand and easing supply pressures slightly, but that limited supply will keep prices elevated for some time.
A loophole in US export controls reportedly lets high-bandwidth memory (HBM) made by Samsung Electronics and SK Hynix reach China's AI chip industry. The loophole shows how much Huawei's next-generation processors still depend on foreign memory, while China's domestic suppliers struggle to close the gap.
Apple's Greater China revenue rose 21% year-over-year to a record US$17.5 billion in the fourth quarter of fiscal 2026, ended September, while full-year revenue increased 28%, driven by the launch of the iPhone 18 Pro series. The results underscore the flagship iPhone's continued competitiveness in China, while rising memory prices threaten to pressure profit margins and growth.
DRAM manufacturer Nanya Technology reported consolidated revenue of NT$46.476 billion (US$1.42 billion) in October 2026, up 3.07% from September and 487.73% year-over-year. Driven by continued increases in DRAM prices, monthly revenue reached a record high for the 12th consecutive month. Consolidated revenue for the first 10 months totaled NT$311.761 billion, up 602.15% year-over-year.
Samsung Electronics' and SK Hynix's dependence on sustained AI infrastructure spending is bringing customer financing risk into focus. As demand for high-bandwidth memory and server DRAM lifts their businesses, industry discussion of possible financial support for AI customers raises a further issue: protecting future chip orders could also expose suppliers to customers' investment risks.
SK Hynix's plans for a US$45 billion NAND investment in New York face a regulatory hurdle as Washington holds back approval for American chipmaking equipment needed at the company's Dalian plant in China, putting the proposed US expansion under pressure ahead of a year-end tax incentive deadline.
AI data centers are increasing demand for high-speed optical communications, making optoelectronics supply chains increasingly strategic. Marvell's announced acquisition of Lumentum highlights chipmakers' growing integration of optical technologies. Huawei has pursued its own supply-chain strategy through sustained equity investments by Hubble Technology.
More coverage